Last week’s note showed different resins moving at different speeds. This week the PVC story got much clearer — and it is not a bearish one. While futures pulled back on macro noise, the physical market tightened: operating rates hit a year’s low, warehouses drained at the fastest pace in months, and producers sank deeper into losses. For film buyers in Southeast Asia, this is the setup where quotes stop falling and start climbing.
1. The week in numbers
| Marker | Level | w/w | y/y |
|---|---|---|---|
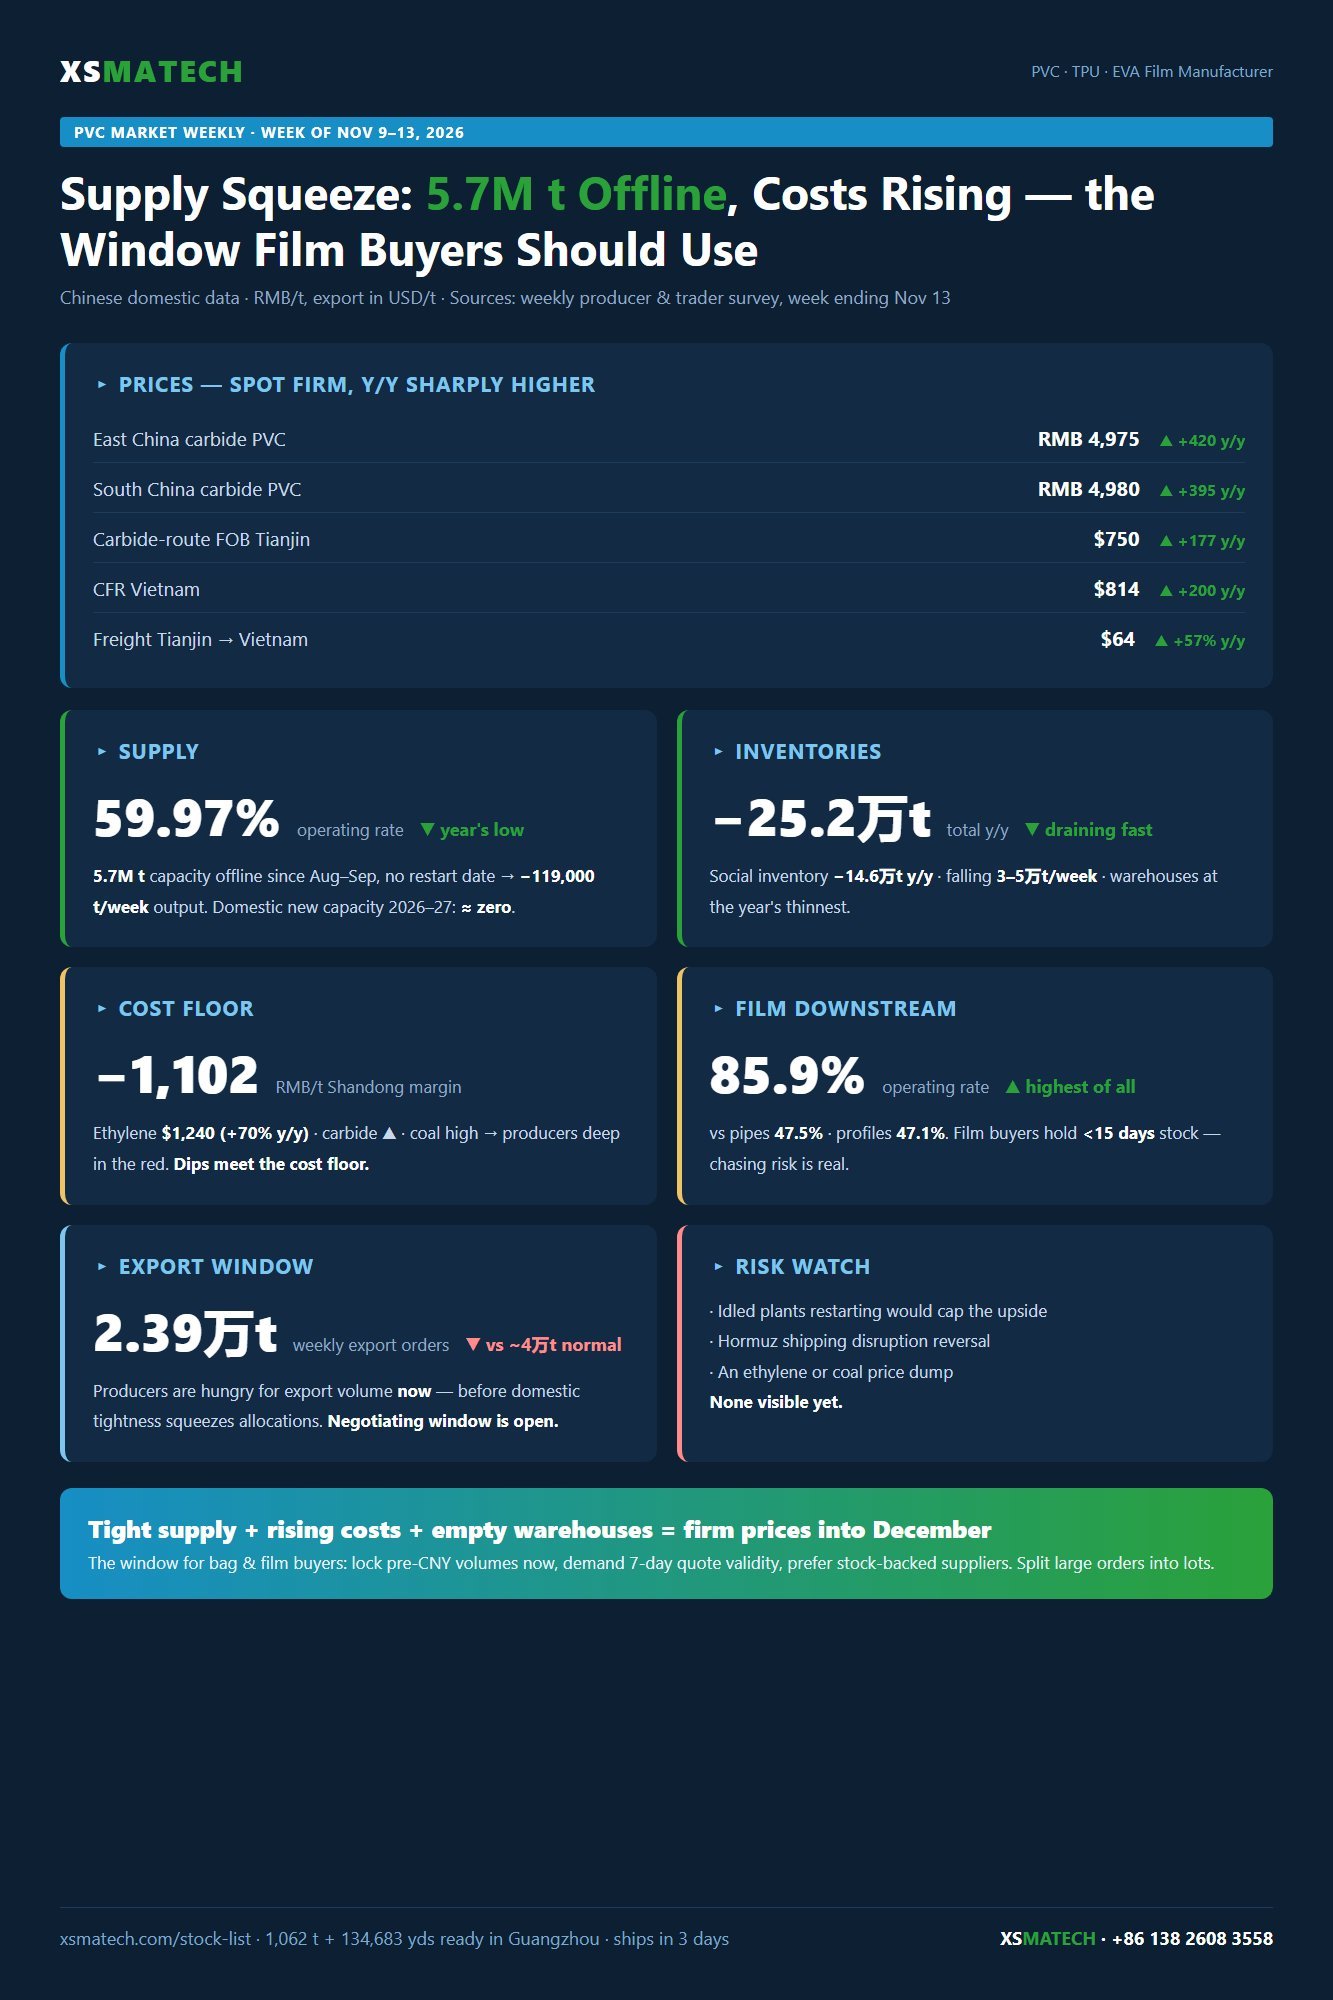
| East China carbide-route PVC | RMB 4,975/t (≈ $700) | +20 | +420 |
| South China carbide-route PVC | RMB 4,980/t | −80 | +395 |
| Futures, main contract | 4.931 | −131 | +345 |
| Carbide-route FOB Tianjin | $750 | −10 | +177 |
| Ethylene-route FOB Tianjin | $830 | 0 | +255 |
| CFR Vietnam | $814 | −6 | +200 |
| Freight, Tianjin → Vietnam | $64 | +4 | +23 |
Spot held mostly flat-to-firm week on week, but every year-on-year line is sharply higher. Futures dipped on macro sentiment — the physical market did not follow.
2. 5.7 million tonnes of supply is offline
- Upstream operating rate: 59.97% — the lowest of the year, roughly 20 percentage points below the same period in 2025.
- Plants idled in August–September (5.7 million t of capacity) still have no restart date; that alone removes ~119.000 t of output every week.
- Winter maintenance is light (December: only one major producer scheduled), but the standing gap persists — the next three weeks are expected to run at 59–62% utilization.
- Capacity additions: domestic 2026–2027 ≈ none. Overseas is also empty until 2027 (UAE project 2028–29; Indian expansions 2027–28).
Translation: the supply gap cannot fix itself this quarter.
3. Warehouses are emptying fast
- East China social inventory: 75.64 kt, −3.06 kt w/w.
- Social inventory y/y: −14.56 kt; total (social + upstream) y/y: −25.23 kt — the fastest drain of the year.
- Even if idled plants restart, inland-to-coast logistics lags weeks behind. Tightness should hold through November–December.
4. The cost floor is real
- NE Asia ethylene: $1,240/t, up ~70% y/y — ethylene-route producers are deeply unprofitable.
- Carbide prices rose another RMB 100–150; thermal coal stays high → carbide-route cash costs keep climbing.
- Shandong carbide-route cash margin: ≈ −RMB 1,102/t (≈ −$155). Producers are losing money at today’s prices — which means they will not chase the market down. Any dip meets the cost floor.
5. Film is the busiest corner of the PVC world
South China downstream operating rates this week:
| Segment | Operating rate |
|---|---|
| Film (our segment) | 85.9% |
| Sheet / board | 74.6% |
| Cable | 69.5% |
| Pipes | 47.5% |
| Profiles | 47.1% |
Heat-shrink film and sheet makers report continuous new orders, buying strictly day-by-day with stocks held under 15 days. Edge-banders and compounders started locking November volumes on the dip. Film is running hot while holding almost no inventory — when the same buyers chase at once, spot premiums appear fast.
6. What this means for bag & film buyers in SEA
- CFR Vietnam is +$200/t y/y and freight Tianjin → Ho Chi Minh City is up ~57% y/y — landed costs creep upward even when headline prices pause.
- Export orders are still soft (2.39 kt this week vs ~4 kt normal) — producers are hungry for export volume now, before domestic tightness squeezes allocations. This is the negotiating window.
- The only big downside levers (a Hormuz reversal, an ethylene or coal dump) are not visible yet.
7. The 5-move playbook
- Demand a validity window on every quote — 7 days for resin-linked items.
- Prefer stock-backed suppliers — the resin in their warehouse is already priced.
- Lock pre-CNY volumes now — the December–January dispatch window tightens every week.
- Split large orders into 2–4 lots instead of betting on one perfect week.
- Ask which route your PVC comes from — carbide and ethylene have different price engines.
8. How we handle this for you
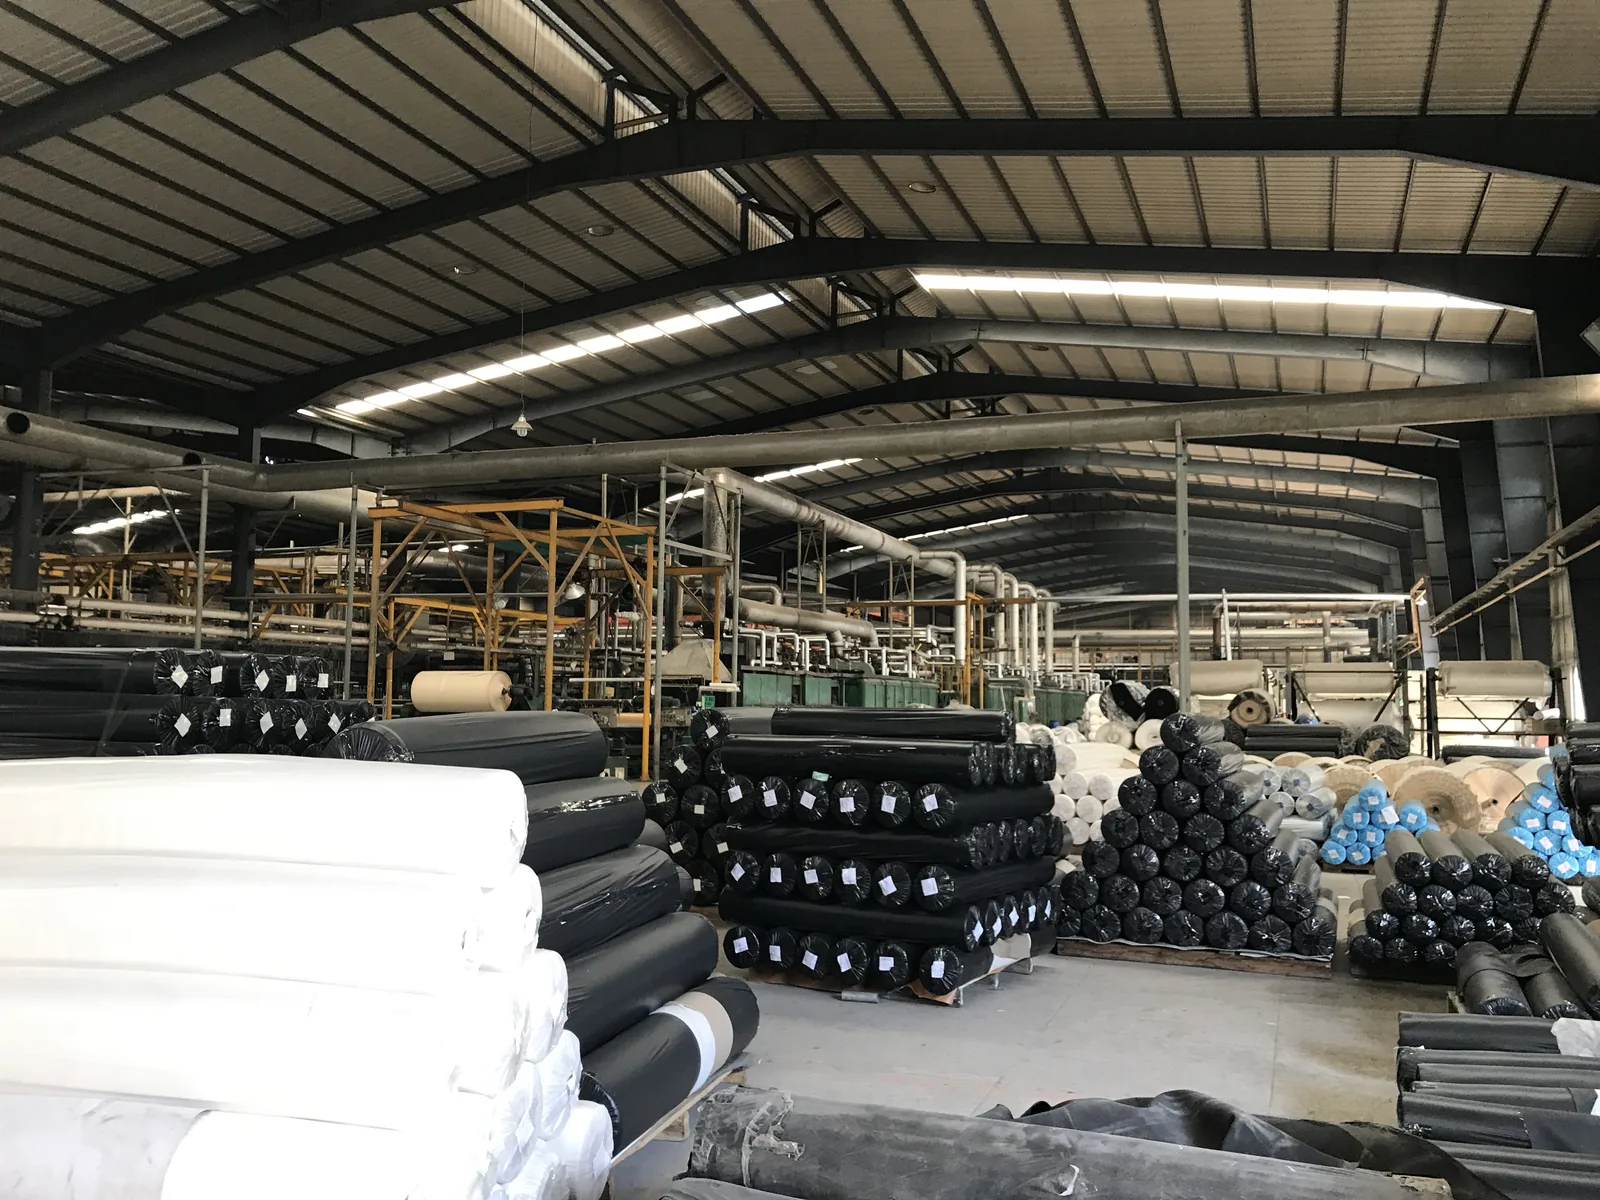
1.062 tonnes + 134.683 yards physically in stock — our quotes are firm, no mystery expiry. Dispatch in 3 ngày from Guangzhou; free samples of standard grades.
Current stock list and today’s firm prices: xsmatech.com/stock-list — or WhatsApp +86 138 2608 3558.